Ibrahim Traoré frequently asserts that Burkina Faso must rely on its own resources and that borrowing is unnecessary for development. This stance is often portrayed as a clean break from past practices: reduced external dependence, enhanced economic sovereignty, and a commitment to funding development from domestic means.
However, public debt figures warrant a more cautious interpretation of this claim.
Behind the political messaging, a fiscal reality is evident: Burkina Faso’s public debt has risen sharply in recent years.
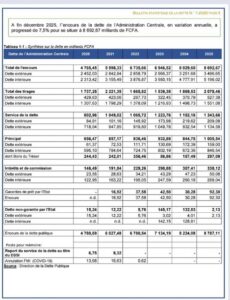
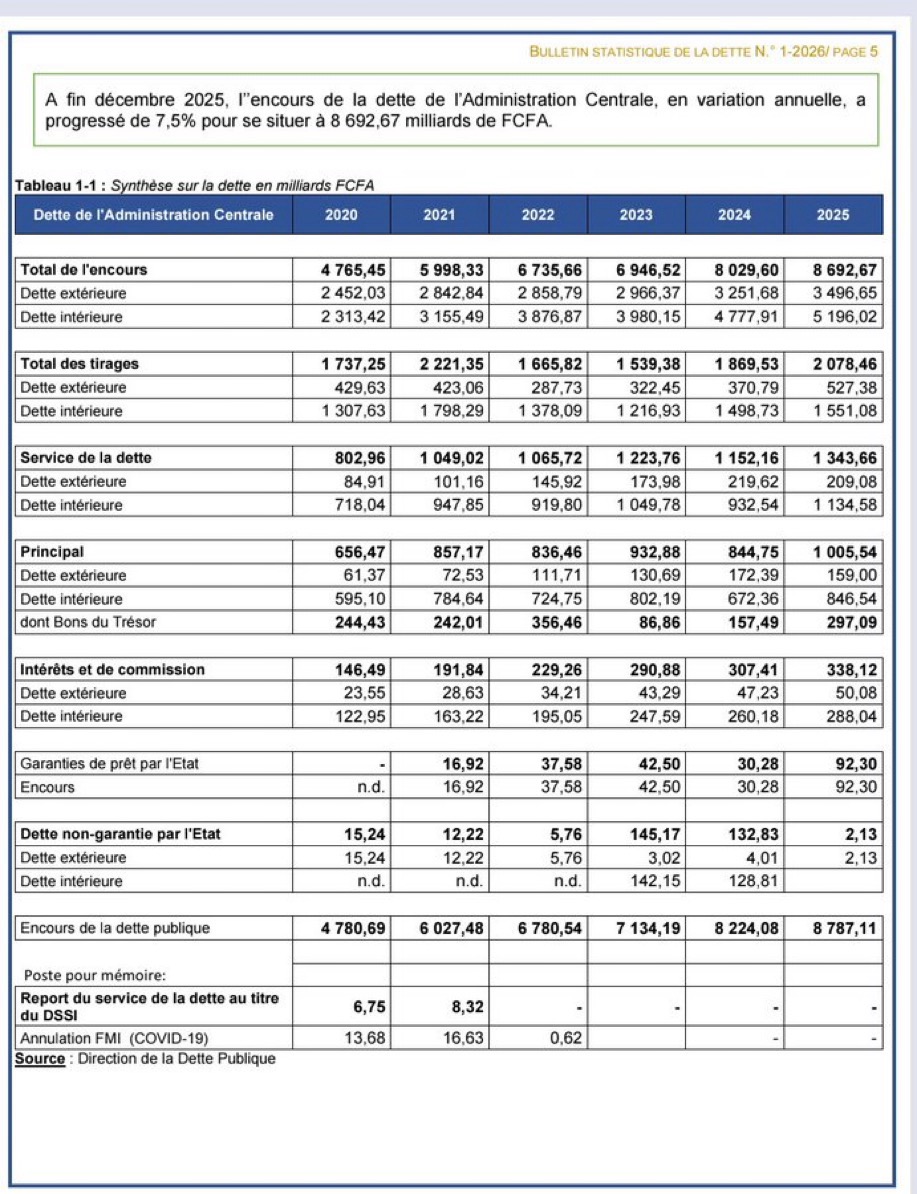
At the end of December 2020, the outstanding debt of the central government stood at 4,765.45 billion FCFA. By the end of 2021, it had already reached approximately 6,107 billion FCFA, as per Ministry of Economy and Finance documents.
The upward trend has continued since.
According to the latest available statistical bulletin from the Burkinabè Treasury, central government debt amounted to 8,692.67 billion FCFA at the end of December 2025. A few months later, by the end of March 2026, it had risen to 8,731.5 billion FCFA.
In other words, within a few years, Burkina Faso’s debt level escalated from under 5,000 billion FCFA at the close of 2020 to over 8,700 billion by 2026.
The paradox of the anti-debt discourse
This raises a critical question.
The issue is not merely whether a state borrows. Public debt does not automatically signal poor management. A government may borrow to finance infrastructure, boost investment, address a security crisis, or sustain public spending when revenues fall short.
The essential query is: what are the new loans used for, at what cost are they acquired, and what future repayment capacity do they generate?
The structure of Burkina Faso’s debt itself merits scrutiny.
By the end of 2025, nearly 60% of central government debt comprised domestic debt, primarily in the form of Treasury bills and bonds. Domestic debt totaled approximately 5,196 billion FCFA.
This shift is significant because domestic financing is not cost-free. Both principal and interest must be repaid. In the first quarter of 2026, debt service already amounted to 407.1 billion FCFA, marking a 31.5% year-on-year increase, based on Treasury data.
Financial sovereignty comes at a cost
Ibrahim Traoré can legitimately advocate for an economic sovereignty policy. Yet sovereignty is not solely measured by rejecting certain partners or making declarations of financial independence.
It is also gauged by a state’s ability to sustainably increase revenues, control expenditures, fund investments, and manage debt service burdens.
Burkina Faso possesses significant mineral resources, notably gold. However, the presence of these resources does not automatically translate into sufficient state liquidity to finance all ambitions without borrowing.
This is where the debate should pivot: the real challenge is not to declare that Burkina Faso will avoid borrowing, but to demonstrate that each borrowed franc generates enough value to justify its cost.
Over 8,700 billion FCFA: the government’s obligation to clarify
The Burkinabè government can highlight its investments, military efforts, infrastructure, or social policies. But these expenditures must be weighed against the debt trajectory.
The International Monetary Fund, in its 2026 analysis, classifies Burkina Faso at moderate risk of debt distress, while deeming the debt sustainable in the medium term. The institution nevertheless points to several vulnerabilities, including refinancing risks for domestic debt, dependence on gold export revenues, and the security situation.
It would be excessive to mechanically present this debt increase as evidence of insolvency. Available data do not support such a conclusion.
Yet it would be equally difficult to argue that the country has developed in recent years without significant reliance on borrowing.
The numbers tell a different story.
Between the end of 2020 and the first quarter of 2026, central government debt increased by nearly 4,000 billion FCFA.
The question that remains is straightforward but politically and economically momentous:
If Burkina Faso does not need to borrow to build itself, how can its public debt have risen by several thousand billion FCFA during this period?
It is this apparent contradiction between the discourse of financial sovereignty and the evolution of public accounts that Ibrahim Traoré’s government must address with precise answers: how much was borrowed, from whom, at what rates, to finance which projects, and with what measurable outcomes for the population?
In public finance, slogans may appeal. The numbers, however, demand explanation.